What's inside
- Compare tab: your household size and income, COBRA's premium/fee/deductible/coinsurance/out-of-pocket max, and the Marketplace benchmark plan plus the plan you'd actually buy
- Your 2026 premium tax credit worked out automatically from the applicable-percentage table, including the hard cutoff at 400% of the poverty line (the subsidy cliff is back for 2026)
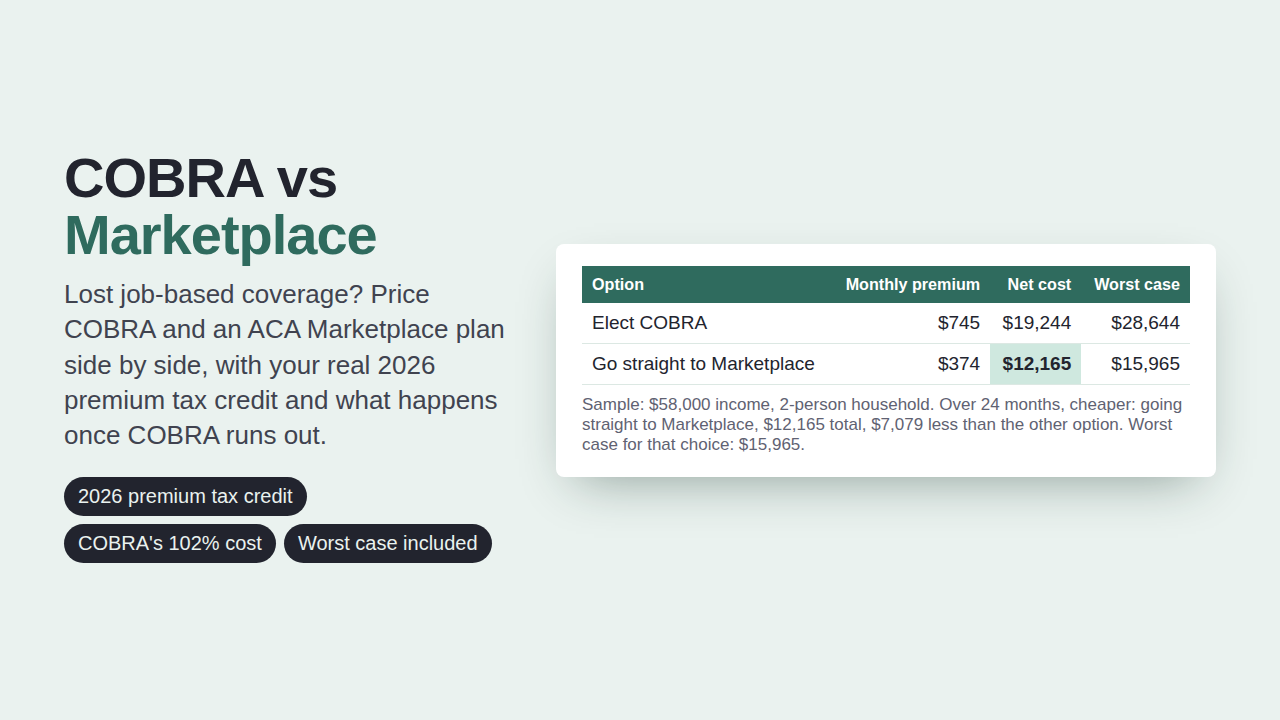
- Side by side over your time horizon: monthly premium now, total premiums, expected out-of-pocket cost, expected net cost and worst case for each option — including the split case where your horizon runs past COBRA's limit and you switch to the Marketplace for the rest
- Workings tab: the full IRS Rev. Proc. 2025-25 premium-tax-credit table and every legal citation (COBRA's 102%-of-premium cap, the 2025 federal poverty guideline), so if Congress changes the rule again only one table needs new numbers
- Sample file: a 2-person household at $58,000 (274% of the poverty line) comparing 24 months — going straight to the Marketplace saves $7,079 over electing COBRA
Checked, not just designed: all 20 formulas recalculate with zero errors, and every result — the poverty-line ratio, the premium tax credit, COBRA's cost, and the side-by-side totals — was checked against an independent Python calculation in 39 scenarios, including every income-band boundary, the 400% cliff, and the COBRA-to-Marketplace switch.
Works in Excel and Google Sheets. Not insurance or tax advice.
Try the free version first
The free online calculator uses the same model for a quick answer. The spreadsheet adds tracking, history and the full views.